

Overview
When you’re buying term insurance, the insurer you choose matters just as much as the policy. Ideally, you want an insurer with a consistently strong claim settlement record, solid financial strength, low complaint volumes, and a sizeable business.
Tata AIA performs decently across most of these metrics. But is Tata AIA term insurance good? And more importantly, is it the right fit for you?
In this guide, we break down the insurer’s key strengths and weaknesses by explaining its term offerings, riders, and performance across key operational metrics. Let’s dive in.
Tata AIA Life Insurance Term Plans
Tata AIA Sampoorna Raksha Promise
Tata AIA Sampoorna Raksha Promise is the insurer's flagship pure term insurance offering. Depending on the selected variant, you can enter the policy between 18 and 65 years, with coverage extending up to 100 years. The minimum sum assured starts at ₹50 lakh, with no predefined maximum, subject to the insurer's underwriting guidelines.
Key Features
- Multiple Plan Options: The plan offers pure protection and return-of-premium structures, including individual and joint-life coverage.
- Terminal Illness Benefit: On diagnosis of a qualifying terminal illness, the plan can accelerate 50% of the effective sum assured, while applicable future premiums are waived.
- FlexiPay: Eligible policyholders can defer premium payments for up to 12 months while keeping their life cover active.
- Instant Payout: For eligible claims, Tata AIA can provide an advance payout of ₹3 lakh within one working day of claim registration, subject to the prescribed conditions.
- Life Stage Cover Enhancement: You can increase your life cover after specified milestones such as marriage (50% of sum assured), childbirth (up to 2 children and 25% each), or taking a home loan (25%) without undergoing fresh medical underwriting, subject to the policy conditions.
- Return of Premium: Under the Plus option, policyholders who survive until maturity can receive 100% of eligible premiums paid back. However, this option comes at a significantly higher premium than pure protection.
- Flexible Death Benefit: The death benefit can be structured as a lump sum, regular income, or a combination of the two, depending on the selected policy option.
Tata AIA Maha Raksha Supreme Select
Tata AIA Maha Raksha Supreme Select is designed primarily for customers seeking high-value life insurance coverage. It is available to individuals aged 18 to 65 years, with protection extending up to 100 years.
The minimum sum assured starts at ₹2 crore, with no predefined upper limit, subject to underwriting. The plan offers pure protection and return-of-premium options, along with a 50% terminal illness payout, waiver of future premiums, FlexiPay, Life Stage cover enhancement, and an eligible ₹3 lakh Instant Payout on claim intimation.
Tata AIA Saral Jeevan Bima
Tata AIA Saral Jeevan Bima is a standardized pure term insurance plan for buyers looking for relatively simple, modest life cover. You can buy it between ages 18 and 65, with coverage extending up to age 70. The sum assured ranges from ₹5 lakh to ₹49.5 lakh, while policy terms can range from 5 to 40 years. It offers regular, limited, and single premium payment options but does not provide the extensive customization available with Tata AIA's flagship term plans.
Tata AIA Bharat Suraksha Cover Micro Insurance
Tata AIA Bharat Suraksha Cover is a micro term insurance plan aimed at customers who need basic, low-cost life insurance protection. You can enter the policy between ages 18 and 50, with coverage available up to age 60. For the non-PoS version, the sum assured starts at ₹20,000, with a maximum cover of ₹2 lakh. The plan offers policy terms of up to 10 years and allows single, regular, or limited premium payments. Optional accident, disability, critical illness, and hospitalization riders are also available.
Key Performance Metrics: Tata AIA Life Insurance
The above data is for the entire life insurance portfolio of the insurer, and it has been sourced from IRDAI annual reports and insurers’ public disclosures. To compare with other insurers, refer to Ditto Data Lab.
Talk to an expert
today and
find
the right
insurance for you.
Riders Offered by Tata AIA Life Insurance
Critical Illness Benefit
Waiver of Premium
Accidental Death Benefit
Accidental Total and Permanent Disability
The rider portfolio is comprehensive, but availability, tenure, waiting periods, and coverage depend on the rider and base-plan configuration. Compare the actual rider terms before adding them simply for additional features.
Note: At Ditto, we recommend opting for the Critical Illness Benefit and Waiver of Premium riders.
Premium Comparison: Tata AIA vs. Leading Insurers
For this example, we’ve considered healthy profiles of non-smoking, salaried individuals living in a tier-1 city like Delhi (pincode: 110010) covered for a sum assured of ₹2 crore until age 65. These premiums are indicative and vary based on your age, sum assured, health conditions, lifestyle choices, riders chosen, and underwriting.
Key Insight: The comparison puts Tata AIA in the middle.
Across these profiles, Sampoorna Raksha Promise is consistently slightly more expensive than Axis Max Life, generally by about 2.5% to 5%. However, Tata AIA remains materially cheaper than HDFC Life across the same profiles.
This means Tata AIA isn't necessarily the best option if your only objective is the lowest premium. But the pricing is still reasonably competitive when weighed against its brand backing, claim performance, and plan features.
Pros and Cons of Tata AIA Life Insurance
Pros of Tata AIA Life Insurance
- Strong Parentage: Tata AIA combines Tata Sons' 51% ownership with AIA Group's 49% stake and international life insurance experience.
- Strong Claim Metrics: Both CSR and ASR are above the industry benchmarks.
- Low Complaint Volume: Tata AIA has consistently maintained just 3 complaints per 10,000 claims, substantially better than the industry average.
- Comprehensive Term Plans: Sampoorna Raksha Promise includes features such as FlexiPay, terminal illness protection, Instant Payout, and Life Stage cover enhancement.
Cons of Tata AIA Life Insurance
- Solvency Is Comparatively Modest: Its three-year average of 1.84x is above the regulatory minimum of 1.5x and above Ditto’s benchmark of 1.8x but below the 2.00x industry median.
- Limited Critical Illness Protection: The Critical Illness (CI) Rider covers fewer illnesses than other insurers. For example, Axis Max Life’s CI covers 64 illnesses.
- Products Can Feel Complicated: Multiple variants, riders, discounts, and conditional features mean buyers need to check exactly what is included in their issued policy rather than relying on the headline feature list.
Who Should Buy Tata AIA Life Insurance?
Tata AIA is worth considering for buyers who value strong claim performance, low complaint volumes, and the backing of established brands like Tata and AIA. Its term plans, especially Sampoorna Raksha Promise, suit customers looking for high coverage, flexible payout options, and features such as FlexiPay, terminal illness protection, and Life Stage upgrades.
Why Choose Ditto for Term Insurance?
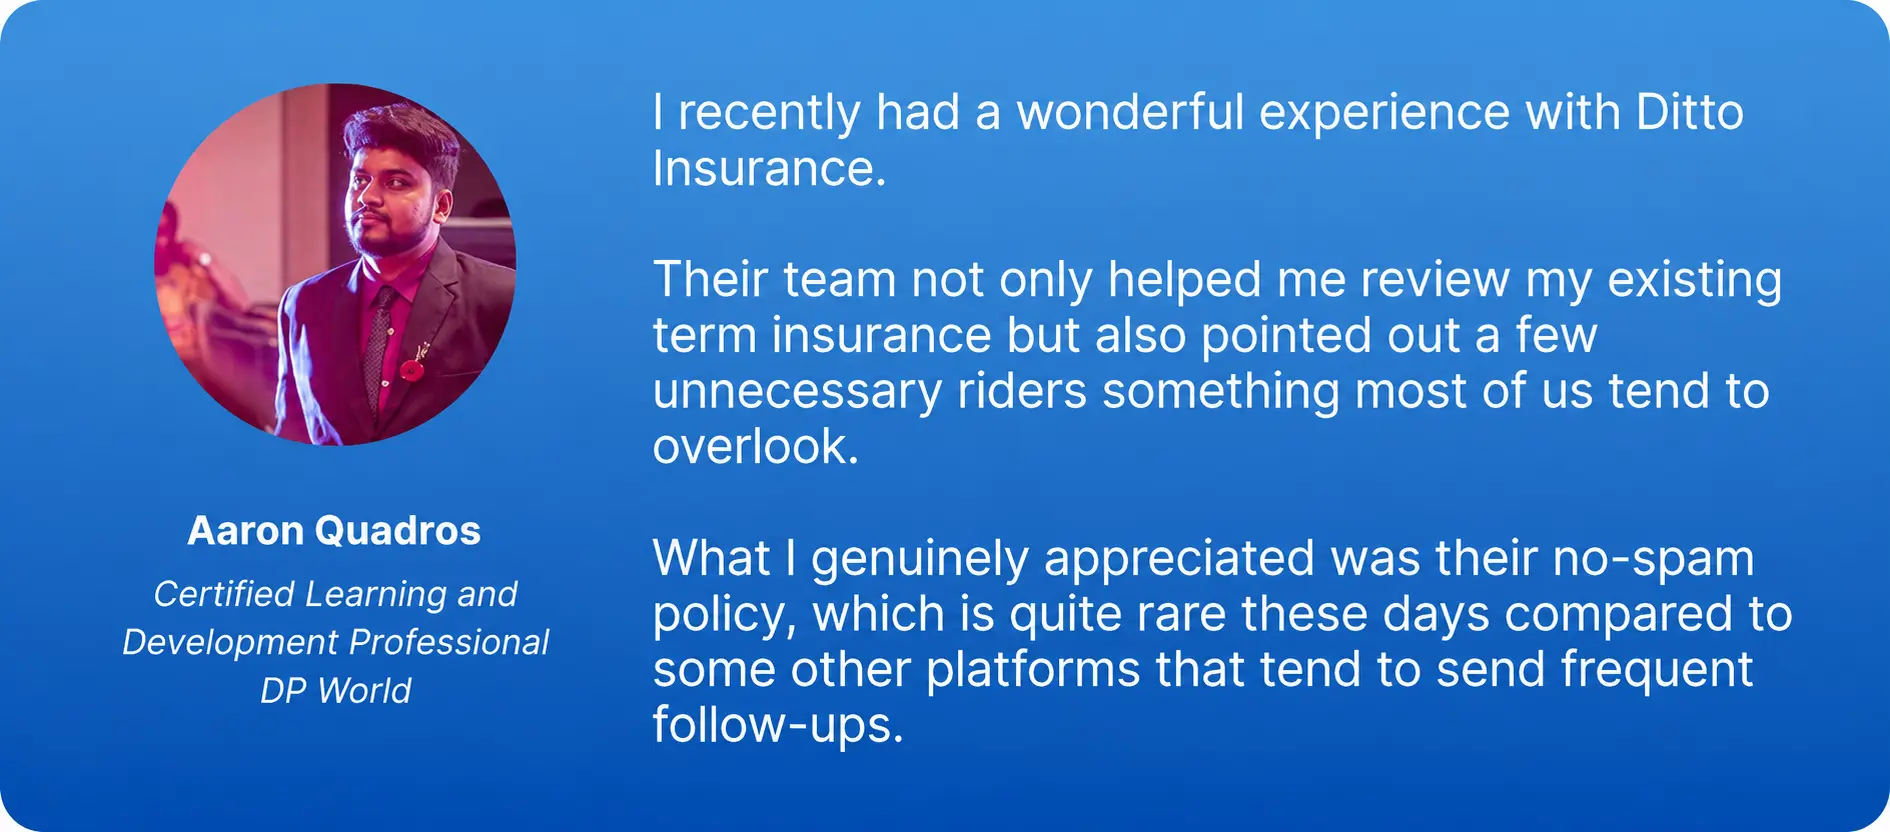
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion: Is Tata AIA Term Insurance Good?
Tata AIA is a credible life insurer with strong claim performance, low complaint volumes, solid parentage, and comprehensive term insurance offerings.
However, Tata AIA isn't our first choice for every profile. Its three-year solvency ratio is relatively modest compared with some leading insurers, premiums are slightly higher than Axis Max Life across sample profiles, and Ditto's current assessment finds room for improvement in post-sales servicing.
So, if Tata AIA offers competitive underwriting terms and you value its product features and brand backing, it's worth shortlisting. But we'd still compare it with Axis Max Life, Bajaj Life, HDFC Life, and other strong alternatives before deciding.
Frequently Asked Questions
Last updated on: