

Overview
SBI Life Insurance Company Limited was incorporated in 2000 and began operations in 2001 as a joint venture between the State Bank of India and BNP Paribas Cardif. While BNP Paribas Cardif was the original international partner, it gradually reduced its stake and exited the company in 2022.
State Bank of India remains the promoter, giving SBI Life the backing of one of India’s largest banking institutions. Today, SBI Life offers a wide range of insurance products across protection, savings, retirement, child insurance, and group insurance.
This guide reviews the key features, premiums, riders, and limitations of an SBI Life insurance term plan.
SBI Life Insurance: Performance Metrics
SBI Term Insurance Plans: Features & Key Differences
1) SBI Life Smart Shield Plus
Smart Shield Plus is a non-linked, pure protection term insurance plan with three coverage options:
- Level Cover: The nominee receives the fixed sum assured if the policyholder dies during the policy term.
- Increasing Cover: The sum assured increases by 5% every year (simple interest) from the first policy anniversary, up to 200%, while the premium remains unchanged.
- Level Cover With Future-Proofing Benefit: Allows the policyholder to increase the cover after specified life events such as marriage, childbirth, adoption, and home purchase, subject to policy limits.
It also offers Accidental Death Benefit (ADB), which provides an additional payout if the life assured dies due to an accident, Accidental Partial Permanent Disability (APPD), which provides a benefit for qualifying permanent partial disabilities caused by an accident, and Better Half Benefit, which provides life cover for the spouse if the primary life assured dies during the policy term, subject to the policy terms.
2) SBI Life Smart Shield Premier
Smart Shield Premier is designed primarily for high-income earners seeking higher life cover, with a minimum sum assured of ₹2 crore. As shown in the sample premiums below, Smart Shield Premier can cost less per ₹1 lakh of coverage for some buyer profiles.
It offers:
- Level Cover: A fixed sum assured is paid to the nominee on death during the policy term.
- Increasing Cover: The sum assured increases by 10% every fifth policy year, up to a maximum increase of 100%.
- Optional Benefits: ADB and APPD benefits are available.
SBI Life does not publish a fixed maximum sum assured for this plan. The final cover is subject to underwriting.
3) SBI Life eShield Insta
eShield Insta offers two options:
- Plan A: Pure term insurance.
- Plan B: Term insurance with return of premium, where 100% of the total base premiums paid are refunded on survival to maturity, subject to the policy terms.
The plan has a maximum 10-year policy term, an entry age of 18 to 50 years, and sum assured options from ₹10 lakh to ₹60 lakh. It does not offer riders or additional in-built benefits.
4) SBI Life Saral Jeevan Bima
Saral Jeevan Bima is a standardized term insurance plan offering ₹5 lakh to ₹25 lakh of coverage for policy terms ranging from 5 to 40 years. It also has a 45-day waiting period for non-accidental deaths. Its standardized features and eligibility criteria make it easier to compare with similar Saral Jeevan Bima plans offered by other insurers.
Note: If you're looking for an SBI term insurance plan with return of premium, SBI Life offers options such as Smart Swadhan Supreme, Smart Swadhan Neo, and Saral Swadhan Supreme. These plans return the eligible base premiums on maturity, subject to their respective policy terms.
SBI Term Insurance Sample Premiums & Factors That Affect the Cost
For reference, here are indicative premiums compared with two popular term insurance plans. The annual premiums below are based on a non-smoker male profile with ₹2 crore cover until age 70, without first-year discounts:
Note: Premiums are indicative and can vary based on underwriting and the policy option selected. Age, sum assured, policy term, smoking status, health, occupation, premium-paying term, selected riders, and payment mode can all influence the final premium. Monthly payment modes can result in a higher total premium than annual payments.
Since individual life insurance policies have been GST-exempt since September 22, 2025, older premium quotes that include GST may no longer reflect the current cost. Use the SBI term insurance plan calculator to get an estimate based on your specific profile.
Talk to an expert
today and
find
the right
insurance for you.
SBI Term Insurance Claim Process: Documents and Steps
If the policyholder dies during the policy term, the nominee can initiate the SBI Life term insurance claim by following these steps:
1) Notify SBI Life: The nominee can intimate SBI Life by calling 1800-267-9090, emailing [email protected], or visiting the nearest SBI Life branch. For detailed instructions on the claim process, required documents, and submission procedure, refer to SBI Life’s claims and maturity services page.
2) Submit the Claim: Complete and submit the claim form along with the required documents.
3) Claim Verification: SBI Life reviews the claim and verifies the submitted information. Claims involving deaths within the first three years of the policy may be subject to further investigation.
4) Claim Settlement: For death claims that do not require investigation, SBI Life is required to settle the claim within 15 days of claim intimation. If an investigation is required, the claim should be settled within 45 days of claim intimation. If the claim is delayed beyond the applicable period, SBI Life must pay interest at the bank rate plus 2%, calculated from the date of claim intimation until the date of payment.
Documents Required for an SBI Life Term Insurance Claim
The nominee may need to submit:
- Completed claim form
- Original policy document
- Death certificate
- Nominee's identity and bank account proof
- Hospital and medical records, in case of death due to illness
- FIR and post-mortem report, in case of accidental death
Note: Provide accurate information about your health, smoking habits, and income when purchasing the policy. Any discrepancies or misrepresentation can affect claim assessment. Suicide within the first 12 months is subject to the policy's suicide clause, under which only 80% of the premiums paid are payable, not the sum assured.
Pros & Cons of SBI Term Insurance Plan
Pros
- Strong Claim Settlement Record: SBI Life reported a 98.76% three-year average claim settlement ratio, reflecting a consistently high proportion of claims settled.
- Flexible Coverage Options: Plans offer Level Cover, Increasing Cover, and Future Proofing options, allowing policyholders to choose coverage based on their needs.
- Optional Benefits: Select plans provide additional protection through benefits such as Accidental Death Benefit, Accidental Partial Permanent Disability, and Better Half Benefit.
- Multiple Plan Options: SBI Life offers different term insurance plans with varying coverage limits, policy terms, and eligibility criteria, catering to different protection needs.
- Online Accessibility: SBI Life provides online options for purchasing and managing policies, making it easier to access policy-related services.
Cons
- Limited Rider Options: SBI Life's term plans do not offer some commonly available benefits, such as a critical illness rider or waiver of premium rider.
- Limited Features in Some Plans: SBI Life's term plans lack several modern features offered by insurers such as HDFC Life, Axis Max Life, and Bajaj Life, including health management and wellness services, terminal illness benefits, premium break options, and an advance portion of the claim amount soon after the claim is reported. Given their pricing, the limited feature set raises questions about their overall value proposition.
- Return of Premium (ROP) Plans Cost More: A considerable portion of SBI Life’s term insurance offerings come with a return-of-premium structure. These plans typically cost 60% to 100% more than pure term insurance, while the maturity payout primarily returns the premiums you have already paid, without generating any additional growth or investment returns.
Why Choose Ditto for Term Insurance?
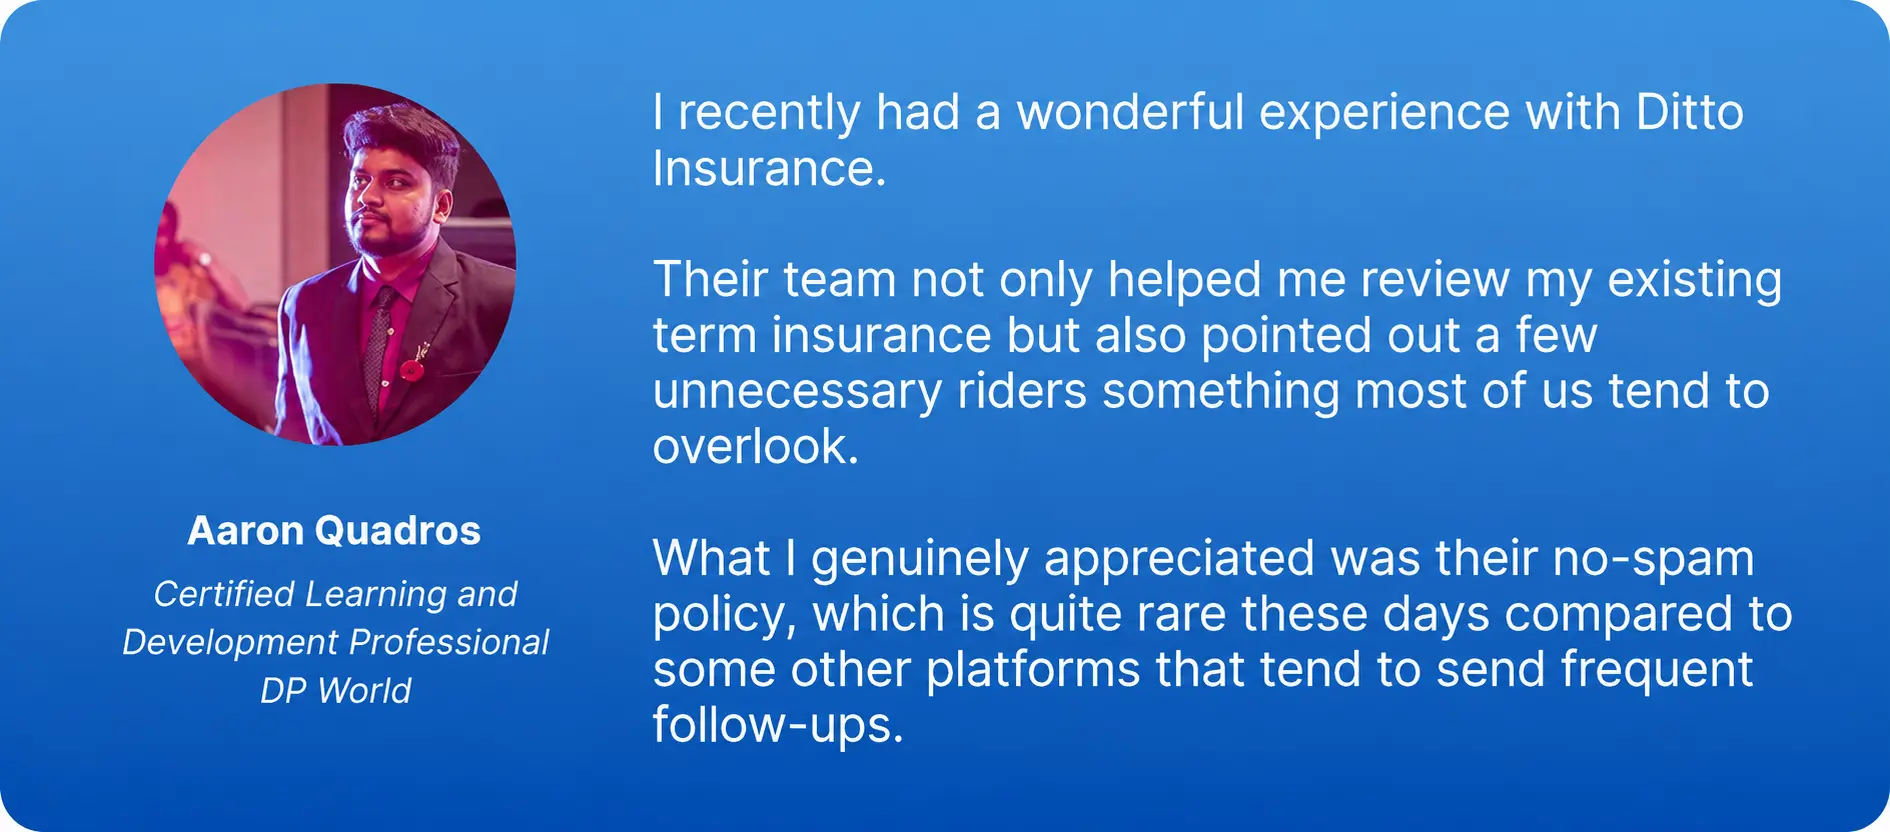
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
SBI Life is the second-largest life insurer in the country and a listed company backed by strong parentage. Its scale, listed status, and long operating history support confidence in its institutional stability.
However, its term plans offer fewer riders and modern convenience features than several newer products. Before buying SBI term insurance, compare its features, riders, claims record, and premiums with other insurers. You can also explore our best term insurance plans guide to compare leading options based on your coverage needs.
Frequently Asked Questions
Last updated on: