

Overview
Choosing between LIC and HDFC Life can be confusing. LIC feels familiar and has enormous reach, while HDFC Life is relatively smaller, but its claims and complaint metrics are stronger.
So, which one is better for your family?
Size alone cannot answer that. You need to compare claims performance, features, riders, premiums, and servicing. In this article, we compare HDFC Life vs. LIC term insurance across all five, so you can choose what works for you.
HDFC Life vs. LIC Term Insurance: Insurer Comparison
HDFC Life and LIC differ significantly in scale, ownership, and distribution reach, with LIC as the largest and HDFC Life as the third-largest insurer by annual business volume.
HDFC Life, established in 2000, is a private insurer promoted by HDFC Bank, with 700+ branches and over 2.7 lakh agents.
On the other hand, Life Insurance Corporation of India (LIC), established in 1956, is a government-majority-owned statutory corporation with a much larger network of 2,000+ branches and more than 14.47 lakh agents, as of March 2026.
Note: Both insurers are listed entities on the stock exchanges.
Features and Rider Comparison: HDFC Life vs. LIC
Both insurers offer multiple term insurance plans. HDFC Life's current lineup includes Click2Protect Supreme Plus, Click2Protect Elite Plus, and Click2Protect Ultimate.
LIC, meanwhile, offers plans such as New Tech Term, Digi Term, and Bima Kavach.
But comparing the number of plans doesn't tell you much. What matters is what you actually get with the policy you are considering.
So, let's compare LIC term plan vs. HDFC Life term plan. For this, we’re considering their flagship offerings: HDFC Life Click2Protect Supreme Plus and LIC New Tech Term on features that can make a practical difference over a 20-, 30-, or even 40-year policy term.
LIC’s New Tech Term Plan is simpler than HDFC’s Click2Protect Supreme Plus. Its core flexibility comes from choosing between level and increasing cover, different premium payment options, and installment payouts. But HDFC’s flagship offering also offers this feature.
That does not automatically make it a bad plan. Some buyers may prefer a simpler term policy. But if features such as instant claim support, a premium break, life-stage increases, terminal illness protection, and wellness services matter to you, HDFC Life Click2Protect Supreme Plus has a clear advantage.
Talk to an expert
today and
find
the right
insurance for you.
Rider Comparison: HDFC Life vs. LIC
- HDFC Life offers multiple comprehensive riders. For example, its critical illness rider covers 60 listed illnesses for up to 15 years, with a 90-day waiting period and a 15-day survival period. It also offers a waiver of premium rider, which waives future premiums upon diagnosis of the same 60 CIs, including disabilities.
Another useful option is the Income Benefit on Accidental Disability Rider, available with the Life Plus option of HDFC Life Click 2 Protect Supreme Plus. If an accident results in total permanent disability, the rider pays 1% of the rider sum assured every month for 10 years, helping replace lost income during a prolonged disability. - LIC offers an accident benefit rider that pays an additional lump sum to the nominee if the insured’s death occurs due to an accident within 180 days of the event.
Note: Other LIC riders exist at the insurer level for other life insurance policies such as ULIPs (Unit-Linked Insurance Plans), savings, or endowment plans, but are not necessarily attachable to the LIC New Tech Term Plan. These include LIC New Term Insurance and LIC Premium Waiver Benefit.
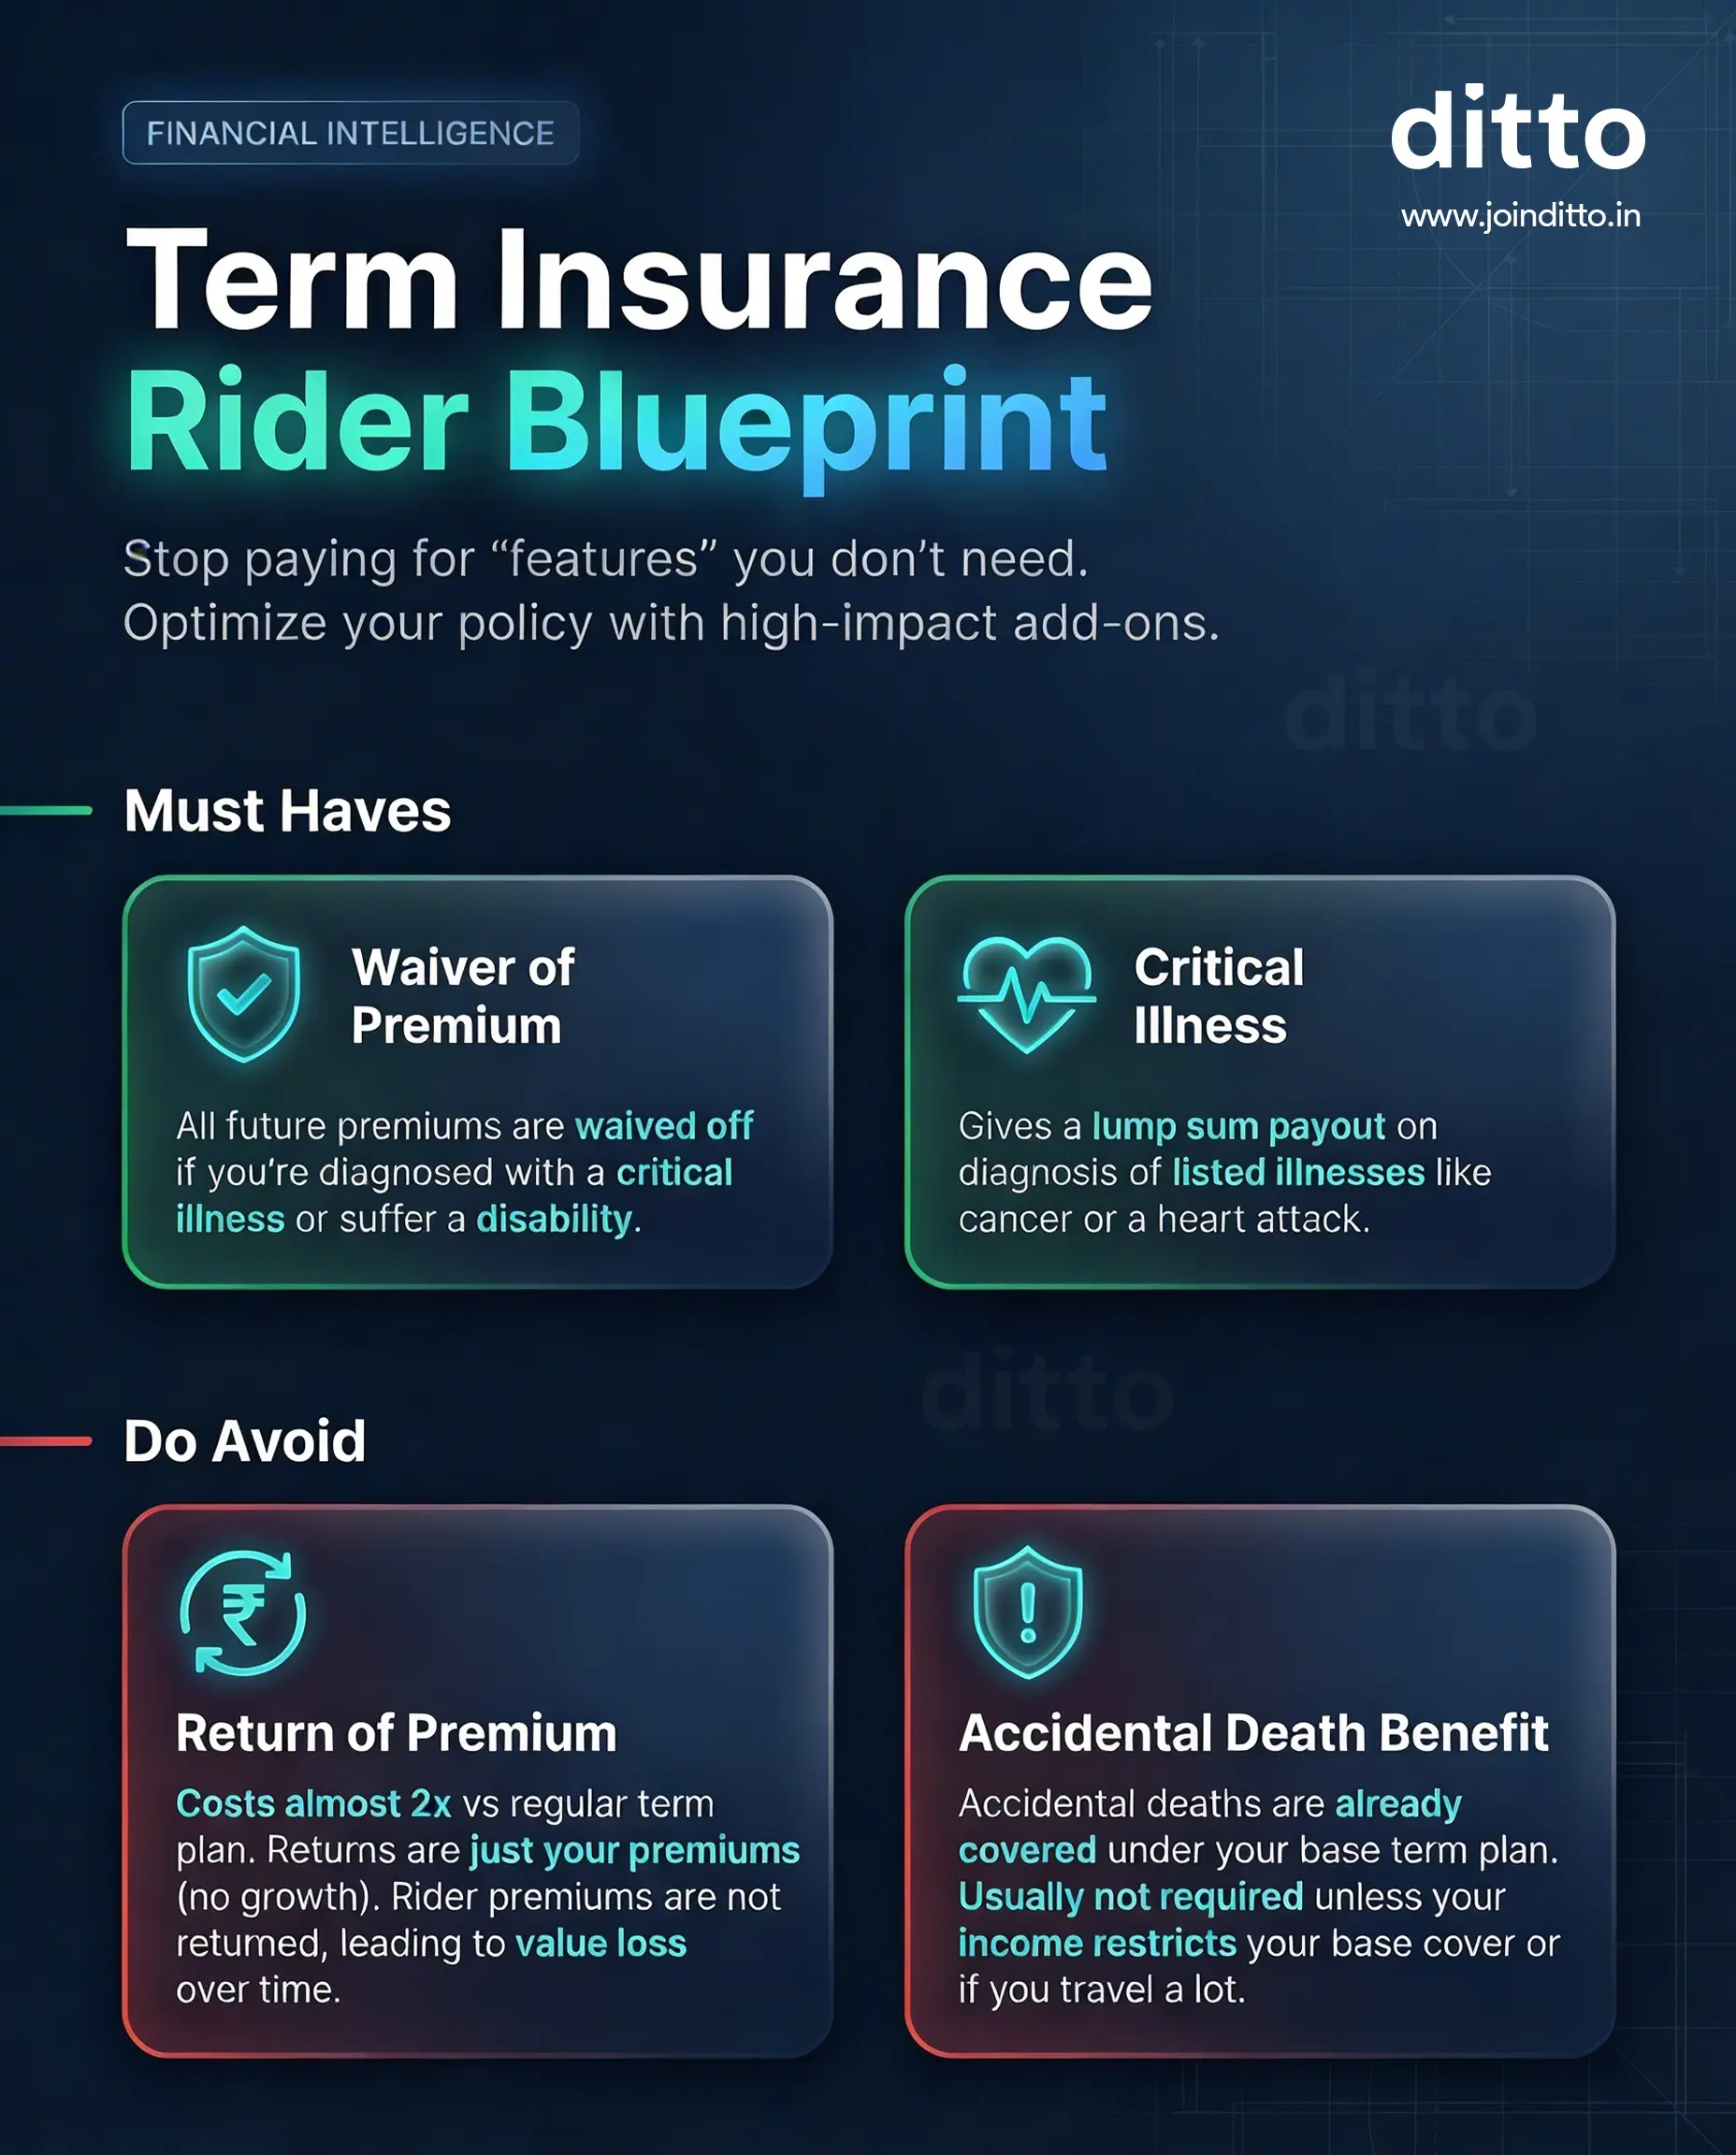
For more details on which riders we recommend at Ditto, you can refer to the attached infographic:
LIC Bima Kavach
Sample Premium Comparison: HDFC Life vs. LIC
For this example, we’ve considered profiles of healthy, non-smoking, salaried individuals living in a tier-1 city like Delhi (pincode: 110010) covered for a level sum assured of ₹2 crore until 65. The above premiums are illustrative and vary based on age, health, tobacco use, occupation, policy term, payment structure, and underwriting. HDFC's pricing can also vary by pincode.
Key Insight: In these sample quotes, HDFC Life is cheaper across all four profiles for the same cover amount and offers more comprehensive inbuilt features.
Performance Metrics: HDFC Life vs. LIC
Sources: The above data comes from insurer public disclosures and IRDAI annual reports. To learn more about what all of this means or how these insurers compare to others in the industry, refer to Ditto Data Lab. The Amount Settlement Ratio (ASR) is for FY 23-25, as the latest year’s metrics haven’t been released yet.
Key Insight: HDFC Life has the stronger operational numbers here. Its average CSR, ASR, and complaint volume are better than LIC's. LIC, however, operates at a dramatically larger scale and has the higher solvency ratio.
Importantly, both insurers comfortably clear Ditto's benchmarks for CSR, ASR, solvency, and complaint volume. So this isn't a choice between a financially strong and weak insurer. HDFC's advantage is stronger claims and complaint metrics, while LIC's advantage is unmatched scale and institutional strength.
Pros and Cons of HDFC Life Term Plans
Pros of HDFC Life Term Plans
- Backed by an insurer with a strong brand value, significant scale, and good claim settlement rates. HDFC Life is operationally efficient, with quick policy issuance, easy access, and relatively low complaint volumes.
- Diverse portfolio of term insurance plans with extensive customization options.
Cons of HDFC Life Term Plans
- HDFC Life may not be the cheapest option for every profile, as competitors like Axis Max Life or ICICI Prudential offer more affordable options.
Pros and Cons of LIC Term Plans
Pros of LIC Term Plans
- Backed by an insurer with unmatched brand recognition, a long operating history, and strong legacy.
Cons of LIC Term Plans
- Premiums are significantly higher for most customer profiles, while rider options such as waiver of premium, critical illness cover, and disability payouts are negligible.
- LIC’s digital servicing capabilities remain less efficient than those of leading private insurers like HDFC Life, which may result in slower policy issuance and operational delays.
HDFC Life vs. LIC: Which Term Insurance Is Better for You?
- HDFC Life is the stronger choice for young salaried and self-employed individuals, particularly those who value flexibility as their income and financial responsibilities evolve.
- Women may also find HDFC Life more competitive based on the sample premiums, although live quotes can vary by age and policy configuration.
- For high-income earners, HDFC Life offers broader customization and protection options, while LIC may suit those who want simpler protection and value its scale and statutory backing.
Why Choose Ditto for Term Insurance?
At Ditto, we’ve assisted over 12,00,000 customers with choosing the right insurance policy. Why customers like Aaron below love us:
- 100% Free Consultation
- No Spam. No Sales Pressure.
- Rated 4.9/5 on Google Reviews by 30,000+ Happy Customers
- Backed by Zerodha
- Dedicated Claim Support Team
- Compare Plans and Premiums with a Trusted Insurance Advisor
Confused about the right insurance? Speak to Ditto’s certified advisors for free, unbiased guidance. Book your call now or chat with us on WhatsApp. Slots fill up fast!
Conclusion
In the LIC vs. HDFC Life comparison, HDFC Life comes out ahead for most buyers looking for a feature-rich term plan. It has stronger recent CSR, ASR, and complaint metrics and offers substantially more flexibility through additional benefits and riders.
On the other hand, LIC remains a credible alternative. It has enormous scale, a much larger physical distribution network, strong solvency, and the statutory backing associated with LIC policies.
Frequently Asked Questions
Last updated on: